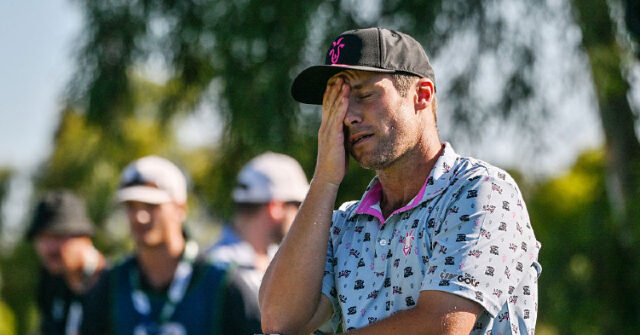
LIV Gold is no more after filing for bankruptcy and revealing that lawyers intend to liquidate the enterprise and dump “LIV 2.0.”
“The debtors are not currently proceeding with the LIV 2.0 plan,” LIV attorney Matthew Williams said in court. “Instead, the debtors are toggling to a value-maximizing wind-down in their business.”
The latest news comes on the heels of reports that LIV’s hoped for investor, BC Partners, decided not to pony up the $300 million infusion of cash into the operation, according to the New York Post.
Several of LIV’s top names had already begun talking about abandoning the league, including Jon Rahm and Sergio Garcia. But LIV spokesman Bryson DeChambeau said he had as many as 30 golfers lined up to join if LIV 2.0 came into being.
Others already involved in the league had hoped to begin negotiations for new contracts.
Speaking of agreements, LIV had already promised to lay out$6.375 million to retain CEO Scott O’Neil as part of a $15.6 million fund to pay seven of its executives. It is unclear what will happen to those deals as the league goes under.
The league has suffered several blows ahead of losing the $300 million investment. First, the league’s Asian Tour fell apart when its partners decided to return to the PGA Tour.
Worse, European Tour chief Guy Kinnings still held animosity toward LIV. They announced that any player who went to LIV tournaments should not bother signing up for the PGA-affiliated event.
Kinnings told a UK newspaper that, “we also have to protect the tour against an entity who spent, so we are told, over $7 billion, with one of their aims being to ‘destroy the DP World Tour.’”
Of course, it all started to go downhill for LIV when its original backer, the Saudi Arabian Public Investment Fund (PIF), decided in April to pull out of its financial commitments to the league.
Follow Warner Todd Huston Facebook at: Facebook.com/Warner.Todd.Huston, Truth Social @WarnerToddHuston, or at X/Twitter @WTHuston